
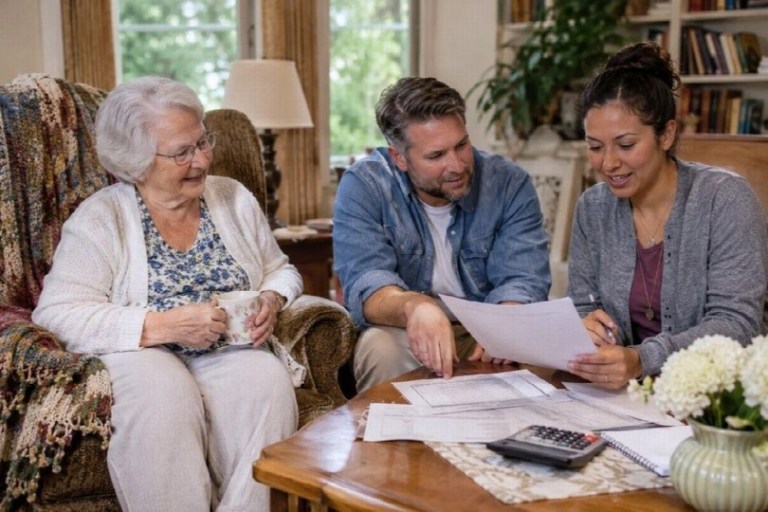
For many families, helping an aging parent remain at home is a top priority. Familiar surroundings, personal independence, and daily routines can make a meaningful difference in a senior’s quality of life. However, understanding the financial commitment of professional in-home care is an important part of making that possible.
The cost of senior care can vary significantly depending on location, the level of assistance required, and the number of hours a caregiver is needed. Some seniors need occasional companionship, while others require daily personal care or around-the-clock supervision.
Understanding these expenses helps families make informed decisions, avoid unexpected costs, and develop a realistic plan for long-term care.
How Much Does In-Home Senior Care Cost?
According to CareScout’s 2025 Cost of Care Survey, the national median cost of non-medical in-home caregiving is approximately $35 per hour. Actual prices can be considerably higher or lower depending on the state and local market.
Genworth Financial, Inc.
At this rate, a senior receiving 20 hours of care each week would spend approximately $3,033 per month. Someone requiring 40 hours weekly could expect to pay approximately $6,067 per month.
For families researching home senior care cost, it is important to remember that hourly rates represent only part of the financial picture. Care needs often change over time, making flexibility an important consideration when planning a budget.
Professional care agencies typically charge hourly rates that account for caregiver wages, scheduling, insurance, supervision, and administrative expenses. Families should request a detailed explanation of services and costs before beginning care.
Different Types of In-Home Care and Their Costs
Not all in-home care services provide the same level of assistance. Understanding the differences can help families choose appropriate services without paying for unnecessary care.
Companion Care
Companion care focuses on social interaction, emotional support, and assistance with everyday activities. Caregivers may help with meal preparation, light housekeeping, errands, transportation, and recreational activities.
This service is often appropriate for seniors who remain relatively independent but would benefit from regular assistance and companionship.
Personal Care
Personal care involves hands-on assistance with essential daily activities. These services may include bathing, dressing, grooming, toileting, and mobility support.
Seniors experiencing physical limitations or difficulty managing personal hygiene often need this additional assistance. Rates depend on the provider, location, and specific care requirements.
Specialized Care
Individuals living with dementia, Parkinson’s disease, or other complex conditions may require caregivers with additional training. These services can involve closer supervision, structured routines, and specialized approaches to communication and safety.
Skilled nursing services, including certain medical treatments, generally cost more and require appropriately licensed healthcare professionals.
What Factors Influence the Price of Senior Care?
Several factors determine what a family ultimately pays for professional care.
Location is one of the biggest considerations. Areas with higher living expenses and greater demand for caregivers generally have higher hourly rates.
The number of scheduled hours also affects monthly spending. Families requesting a few afternoon visits will naturally pay less than those needing daily assistance.
Additional factors include caregiver qualifications, weekend or holiday scheduling, transportation needs, and minimum shift requirements.
Some agencies require visits lasting three or four hours, even when a family needs assistance with only one or two specific tasks. Understanding these policies helps prevent unexpected billing.
The Real Cost of 24-Hour In-Home Care
Around-the-clock care represents one of the largest potential expenses for families supporting an aging loved one.
Seniors who need continuous supervision may require multiple caregivers working separate shifts. This arrangement allows caregivers to remain alert and provide consistent assistance throughout the day and night.
At $35 per hour, continuous care billed for 24 hours daily would cost approximately $25,550 over an average month. Actual pricing depends on staffing arrangements, applicable labor laws, and agency policies.
Live-in care may offer a different pricing structure, but it does not necessarily provide 24 hours of active assistance. Caregivers generally require sleep, breaks, and personal time.
Families should carefully review care schedules and responsibilities before choosing a continuous-care arrangement.
Hidden Expenses Families Should Consider
Professional caregiver fees are not always the only expenses associated with aging at home.
Home modifications may become necessary as mobility decreases. Installing grab bars, improving lighting, adding ramps, or modifying bathrooms can make everyday activities safer.
Medical equipment can create additional expenses. Walkers, adjustable beds, mobility aids, and emergency alert systems may become necessary as care needs increase.
Transportation, medication management, meal delivery, and household maintenance can also contribute to the overall budget.
Families should consider unexpected changes in health that could require additional caregiver hours. Building a financial reserve can help manage these situations without disrupting established care routines.
Does Medicare or Insurance Pay for In-Home Care?
One common misconception is that Medicare automatically pays for ongoing senior care at home.
Traditional Medicare generally does not cover long-term custodial care when assistance with daily activities is the only service required. However, qualifying individuals may receive certain part-time home health services when medically necessary conditions are met.
Medicare+1
Medicaid may help eligible seniors pay for home and community-based services, although benefits and eligibility rules vary by state.
Long-term care insurance policies may cover certain in-home services, depending on their terms and benefit limits.
Veterans and surviving spouses may qualify for assistance through specific Department of Veterans Affairs programs. Families should explore available benefits before assuming all care expenses must be paid privately.
How Families Can Reduce In-Home Care Expenses
Managing senior care expenses does not always mean reducing the quality of assistance.
One effective strategy is to schedule professional caregivers during the hours when help is most necessary. Morning routines, bathing, meals, and transportation are common examples.
Families can also combine professional assistance with support from relatives and friends. This arrangement may help reduce costs while maintaining consistent care.
Periodic care assessments can identify opportunities to adjust schedules as a senior’s needs change.
However, families should avoid cutting essential services simply to reduce expenses. Reliable assistance can help prevent falls, missed medications, caregiver exhaustion, and other problems that may create larger challenges.
Comparing In-Home Care With Assisted Living
Families often compare professional home care with assisted living when planning for future needs.
Assisted living typically combines housing, meals, supervision, and certain personal care services into a monthly fee. In-home care allows seniors to remain in familiar surroundings while receiving individualized assistance.
For seniors requiring only several hours of help each day, remaining at home may be more affordable than moving into a residential community.
However, extensive daily care or continuous supervision can make professional home care more expensive.
Financial comparisons should include existing housing expenses, utilities, meals, transportation, and other household costs. Personal preferences, family involvement, and safety requirements are equally important considerations.
Planning Ahead for Changing Care Needs
Senior care expenses rarely remain exactly the same year after year.
An older adult who initially needs companionship twice weekly may eventually require daily personal assistance. Changes in mobility, memory, or overall health can increase both caregiver hours and monthly expenses.
Families should review care plans regularly and discuss potential changes with their provider. Planning for different levels of assistance can reduce financial surprises.
It is also helpful to involve aging parents in financial discussions whenever possible. Understanding their preferences, resources, and expectations creates a stronger foundation for future decisions.
Making the Right Investment in Senior Care
The true cost of in-home senior care extends beyond the amount printed on a monthly invoice.
Professional caregivers can provide meaningful companionship, improve daily safety, support personal independence, and offer families greater peace of mind.
Choosing the right care arrangement requires balancing affordability with the level of assistance a loved one genuinely needs.
By understanding pricing, exploring financial assistance, and preparing for changing circumstances, families can make informed decisions that support both their financial well-being and their loved one’s quality of life.